COBRA vs. ACA Marketplace in 2027: Which Should You Choose After Leaving a Job?
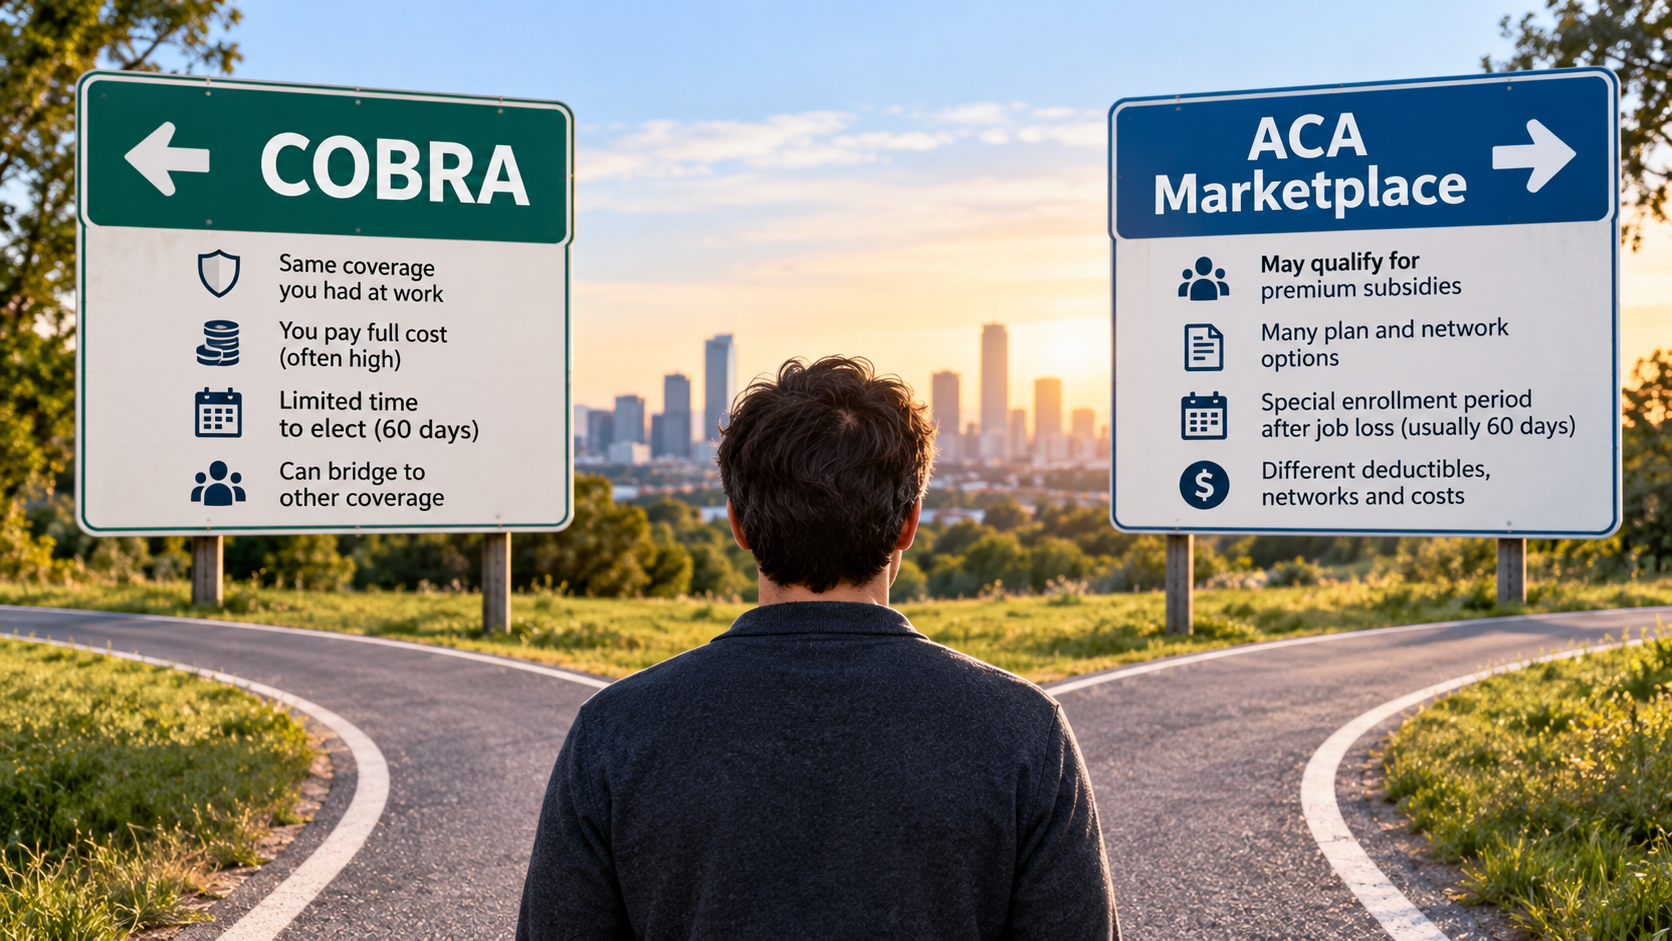
After leaving a job, you may be able to keep your employer’s health plan through COBRA or buy replacement coverage through the ACA Marketplace. The right choice for 2027 depends on more than the monthly premium: compare what you will pay for care, which doctors remain covered, how much of your current deductible you have already met, and when the replacement plan can begin.
COBRA usually costs more because the former employee takes over the employer’s share of the premium. But someone in the middle of expensive treatment can sometimes spend less by staying on the existing plan, while a person expecting little medical care may save considerably by switching to a Marketplace policy.
What You Are Actually Comparing
Federal COBRA generally applies to employer health plans covering 20 or more employees, with certain exceptions; some states offer continuation rights for smaller employers. After a qualifying job loss or reduction in hours, COBRA usually allows up to 18 months of continued coverage, and the charge can reach 102% of the plan’s total cost, including what the employer previously paid. A severance agreement may temporarily cover part of that bill, so request the actual COBRA premium and election notice rather than estimating from your former paycheck deductions.
COBRA preserves the employer plan’s benefits, provider network and deductible and out-of-pocket accounting for the same plan year, subject to changes that also apply to active employees. A new Marketplace policy starts with its own plan terms and cost sharing, even if the insurer’s name is familiar. Verify whether the current plan year and the calendar year coincide: keeping COBRA past a plan-year reset does not preserve last year’s deductible spending indefinitely.
Losing qualifying job-based coverage also generally opens a 60-day Marketplace Special Enrollment Period, whether you quit or were laid off. Marketplace premiums depend on location, ages, plan choice and household income, and the application may identify premium tax credits or Medicaid eligibility. Declining COBRA does not by itself disqualify you from Marketplace subsidies; the IRS specifically addresses this in Question 20.
Three Worked Examples: When Each Option Costs Less
These are constructed examples, not quoted 2027 insurance prices or estimates of typical premiums. They compare premiums over the stated coverage period plus the additional medical expenses a household expects to pay under each plan; the expenses are assumptions, not automatic deductible charges. Actual comparisons must use the COBRA election notice and available Marketplace plans for the household’s ZIP code.
1. A Healthy Worker Needs Six Months of Coverage
Suppose someone leaving work expects to need insurance for six months before a new employer’s benefits begin. COBRA costs $740 per month, while an eligible Marketplace plan costs $330 per month after an assumed premium tax credit. The six-month premium totals are $4,440 for COBRA and $1,980 for Marketplace coverage, a $2,460 difference before medical bills.
If the worker expects little care, the Marketplace savings may outweigh the disadvantage of beginning a new deductible. That conclusion changes if an important doctor is out of network, prescriptions cost much more on the new plan, or actual income makes the projected subsidy unavailable. Check the final net premium and covered services rather than selecting the cheaper figure alone.
2. A Family Has Already Paid Most of Its Annual Medical Costs
Consider a family changing coverage on September 1 with four months left in the calendar-year plan. Their COBRA premium is $1,900 per month, and they expect only $600 more in covered, in-network patient costs before reaching their current out-of-pocket maximum; their projected September-December total is $7,600 in premiums plus $600 in medical bills, or $8,200. A new Marketplace plan costs $1,150 per month, but the family projects $5,500 in covered, in-network expenses under that plan’s fresh cost-sharing schedule: $4,600 plus $5,500, or $10,100.
Under those assumptions, COBRA costs $1,900 less even though its monthly premium is $750 higher. The family’s calculations depend on the expected services, each plan’s actual covered charges, and whether the COBRA plan’s out-of-pocket maximum really is nearly reached. Check how the figures change after January 1, when calendar-year deductibles and out-of-pocket limits commonly reset.
3. An Early Retiree Cannot Count on a Subsidy
Imagine a 61-year-old with an expected 2027 household income of $72,000 who needs 12 months of coverage and is filing as a single person in the contiguous United States. That exceeds the standard 2027 federal premium-tax-credit income ceiling of $63,840 for a one-person household, so the retiree should not build a comparison around a federal Marketplace subsidy. At hypothetical full premiums of $1,120 a month for COBRA and $930 a month for a Marketplace plan, the annual premium totals are $13,440 and $11,160, respectively, a $2,280 Marketplace advantage before medical expenses.
Neither price alone answers whether the retiree’s doctors, drugs and expected treatments make that choice sensible. COBRA also has a limited duration, so it generally cannot bridge four years from age 61 to Medicare eligibility at 65. Our 2027 ACA subsidy income-limits guide explains how the income ceiling works, including differences for household size and state.
The Deadline Trap: A COBRA Decision Can Close Off a Later Switch
COBRA generally gives an eligible person at least 60 days to elect coverage, measured from the later of the loss of coverage or the election notice, and at least 45 days after electing to make the first payment. Properly elected and paid COBRA can operate retroactively to the loss of coverage, but that first payment may cover multiple months. The Department of Labor’s COBRA FAQs explain the election and payment requirements.
Marketplace coverage after losing an employer plan generally begins the first day of the month after that coverage ends; it ordinarily will not cover earlier dates retroactively. If employer coverage ends partway through a month, ask the plan administrator and Marketplace about the exact dates before assuming the two options begin on the same day. Documents establishing the loss of coverage may also be required before the Marketplace policy can be used.
Most importantly, voluntarily cancelling COBRA outside Marketplace Open Enrollment generally does not create a new Special Enrollment Period. Exhaustion of COBRA, certain involuntary losses of continuation coverage, or the end of an employer COBRA contribution may provide enrollment rights, but simply deciding that the premium is too high ordinarily will not. Review HealthCare.gov’s COBRA switching rules before allowing coverage to lapse.
How a Job Loss Changes ACA Subsidies in 2027
Marketplace premium tax credits are based on projected full-year tax-household income, rather than just the wages received after losing a job. Salary earned before separation, severance, unemployment compensation, investment income and taxable retirement distributions can all affect the result. Our guide to what counts as income for 2027 ACA subsidies covers the household-income calculation.
Under current federal rules, the temporary expansion of credits above 400% of the poverty level ended after 2025, and tax years beginning after 2025 no longer have the previous limits on repayment of excess advance credits. If an income estimate is too low, part or all of the advance subsidy may have to be repaid at tax time. Consider taking a smaller advance credit when income is uncertain, and update the Marketplace when circumstances change.
What to Obtain Before You Choose
- From your former employer: the actual monthly COBRA premium, the date employer coverage ends, the election deadline, any severance subsidy and the current deductible and out-of-pocket amounts already credited.
- From Marketplace plan listings: the net monthly price after any verified tax credit, full price without that credit, covered doctors and prescriptions, deductible, out-of-pocket limit and earliest effective date.
- From your care calendar: expected appointments, procedures, prescriptions and treatment needs through the end of the current plan year, then a fresh comparison for the next year.
- From other coverage options: whether you can join a spouse’s employer plan through its separate special-enrollment rights, or qualify for Medicaid or CHIP.
For each option, calculate monthly premium multiplied by the months you need coverage, plus the medical costs you realistically expect to pay under that specific plan. Run a second comparison using the plan’s out-of-pocket limit as a stress test, allowing for what the limit actually covers and excluding premiums. Make the election only after confirming coverage dates; an inexpensive plan that starts too late, or excludes necessary treatment, can be the more expensive outcome.