Medicare Open Enrollment 2027: What to Do If Your Plan Is Ending or Changing
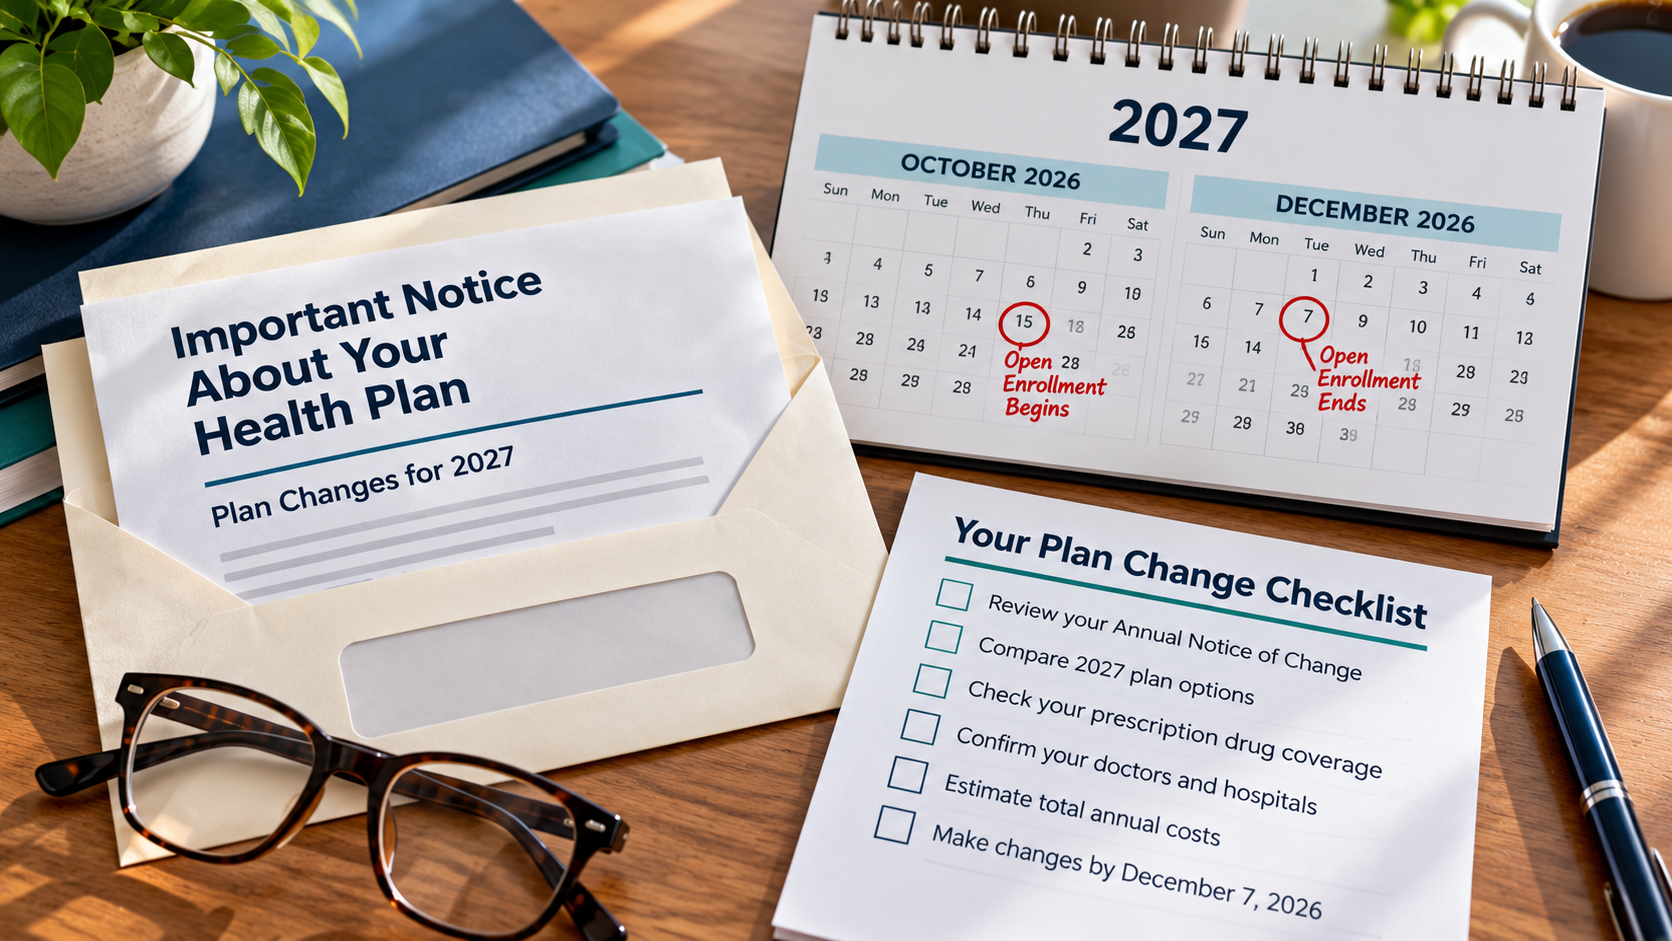
If your Medicare Advantage or Part D drug plan is ending on December 31, 2026, you need to choose what will replace it for 2027. If the plan is continuing but changing its premiums, doctors, drug coverage or cost sharing, you have a different decision: whether the revised plan still meets your needs. Medicare’s annual Open Enrollment runs October 15 through December 7, 2026, and changes made during that period generally take effect January 1, 2027.
Start with the letter from your insurer, then compare the plans actually available at your address using Medicare’s Plan Finder. An insurance company offering Medicare Advantage coverage somewhere in your state does not mean your particular plan will exist in your county next year.
First, Find Out Whether Your Plan Is Ending or Changing
A plan’s Annual Notice of Change, ordinarily sent in September, explains what will change in January if the plan continues. A nonrenewal notice means coverage under that plan will end instead. Keep the letter: the precise reason for the ending determines your enrollment options and may establish special rights to buy a Medicare Supplement (Medigap) policy.
| What the notice says | What to check or do |
|---|---|
| Plan continues for 2027 | Compare the new premium, drugs, pharmacies, provider network, prior authorization and medical out-of-pocket limit. Your current coverage may renew, but the benefits may change. |
| Plan will not renew | Choose a replacement Medicare Advantage plan if available, or examine Original Medicare, separate Part D coverage and Medigap eligibility. Do not assume drug coverage follows you automatically. |
| Insurer consolidates or transfers plans | Read the notice for any proposed automatic reassignment and the replacement plan’s exact ID and terms. Compare it with other available options before the deadline. |
KFF’s October 9 analysis of federal plan files found that the average beneficiary can choose among 28 Medicare Advantage plans with prescription coverage for 2027, but 193 counties have no such plans available for general enrollment. CMS expects the national number of Medicare Advantage plans to remain relatively stable, yet national averages cannot tell you whether your existing plan will renew locally.
If Your Medicare Advantage Plan Is Not Renewed
For a Medicare Advantage plan that ends December 31, you can select another plan during the October 15–December 7 annual enrollment period. Medicare also lists a Special Enrollment Period for nonrenewed contracts running from December 8 through the end of February of the following year. Different rules apply to an early contract termination or other exceptional event, so check the reason stated in your notice before relying on that extended window.
If you do not join another Medicare Advantage plan before your current plan ends, Medicare says you will be enrolled in Original Medicare. That changes how medical care is covered and can leave you needing a separate Part D drug plan; check your prescription coverage rather than assuming your former Medicare Advantage drug benefit continues. A replacement Medicare Advantage plan also needs to cover your service area and, if you require it, include acceptable drug coverage.
If only your stand-alone Part D drug plan is ending, that does not cancel Original Medicare Parts A and B. You may need to choose a replacement Part D plan to maintain prescription coverage in January; check the notice for any automatic reassignment rather than assuming it will happen. A lapse in creditable prescription coverage may also carry a later enrollment penalty, depending on your circumstances.
Plan nonrenewal may give you federal guaranteed-issue rights to Medigap if you return to Original Medicare, even when you are long past your initial Medigap enrollment window. Medicare’s Medigap eligibility guide sets out the qualifying situations and deadlines; eligible applications can generally be submitted beginning 60 days before the Medicare Advantage coverage ends and no later than 63 days afterward. The policies you can buy depend on the applicable federal and state rules, so confirm your specific right before selecting Original Medicare.
If Your Plan Is Staying but the Benefits Are Changing
List your regular medications with dosage and pharmacy, all important doctors and hospitals, and treatments already scheduled for next year. Check each item against the new plan’s formulary, pharmacy network, provider directory and Evidence of Coverage; confirm a particularly important specialist directly with the provider.
Compare expected annual spending rather than sorting plans only by premiums. For example, suppose Plan A has a $0 additional monthly premium but your estimated covered prescription cost is $90 per month, while Plan B has a $35 additional premium and $25 in expected monthly prescription costs. Ignoring medical bills and the Part B premium common to both options, Plan A totals $1,080 for the year and Plan B totals $720, an estimated $360 saving with Plan B despite its higher listed premium.
Those numbers are illustrative, not actual 2027 plan quotes: drug spending may not be evenly distributed across the year, and plan coverage stages, pharmacy prices and medical benefits can change the result. Medicare’s Plan Finder can compare each actual prescription and pharmacy combination. Pay particular attention to prior authorization, specialty drugs and the plan’s maximum annual cost for covered medical services, which is separate from the Part D drug spending limit.
Do Not Confuse Medicare Open Enrollment With Medigap Enrollment
The October 15–December 7 period lets you change Medicare Advantage and Medicare Part D coverage or move between Medicare Advantage and Original Medicare. It does not automatically give everyone a right to buy Medigap without health underwriting. Leaving a continuing Medicare Advantage plan voluntarily can therefore be harder than leaving a plan that has stopped serving your area.
If you are considering Original Medicare, review our Medicare versus Medicare Advantage comparison for the costs, networks and Medigap issues, then verify your actual eligibility with Medicare or your state insurance department. Separately, people already enrolled in Medicare Advantage have a January 1–March 31 Medicare Advantage Open Enrollment Period with more limited switching options; it is not a substitute for reviewing a plan termination before year-end.
Your 2027 Plan Review: Six Checks Before December 7
- Read the notice. Determine whether the plan renews, terminates, or consolidates. Keep the notice and its stated effective date.
- Verify replacement choices. Use your exact ZIP code and coverage situation in Medicare Plan Finder, rather than relying on a national premium average.
- Check doctors and hospitals. Confirm key providers and any referrals, prior authorizations or out-of-network charges.
- Compare prescriptions. Enter drug names, dosages and pharmacies, then examine total estimated yearly drug costs.
- Price the full year. Compare premiums, predictable copays, deductibles, drug bills and a higher-cost medical scenario, not just the advertised premium.
- Protect switching rights. If moving to Original Medicare, verify Part D and Medigap eligibility and deadlines before assuming a supplement will be available.
If the nonrenewal notice is unclear, call the plan and ask whether it is a contract nonrenewal, a service-area withdrawal or a consolidation. You can also contact 1-800-MEDICARE or your State Health Insurance Assistance Program for free, independent help. Ask the representative to identify the specific enrollment period available to you and the effective date of any new coverage.